Key takeaways
- Every company registered in India, other than a one person company, must hold an Annual General Meeting (AGM) each year under Section 96. Being privately held creates no exemption.
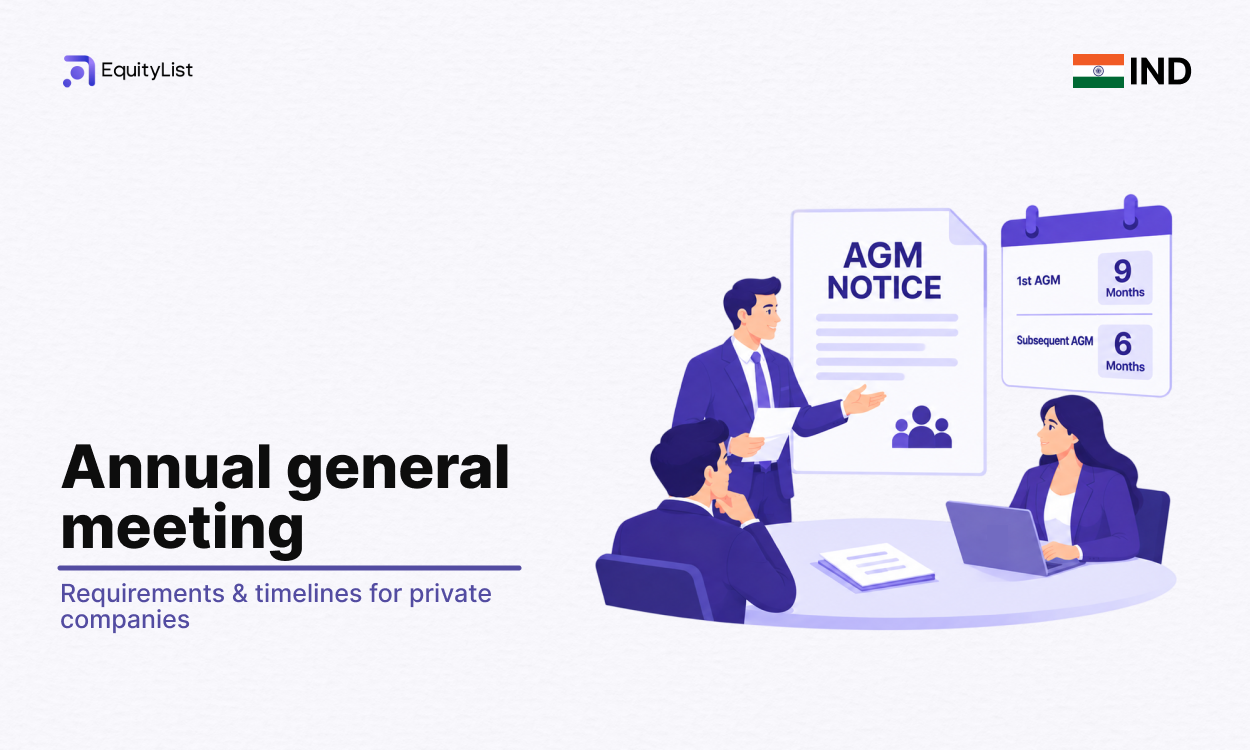
- A company's first AGM is due within nine months of its first financial year's close, and every AGM after that within six months. No more than fifteen months can pass between two AGMs.
- The Registrar of Companies can extend a non-first AGM's deadline by up to three months for a special reason, using Form GNL-1.
- For a private company, AGM quorum is two members personally present, unless the articles set a higher number.
- Missing the AGM deadline exposes the company and every officer in default to a fine of up to ₹1,00,000, plus up to ₹5,000 for each day the default continues, under Section 99.
- Filings anchored to the AGM date include Form MGT-7 (60 days), Form AOC-4 (30 days), and Form ADT-1 where an auditor is appointed at the meeting (15 days).
What is an Annual General Meeting (AGM)
An Annual General Meeting is a general meeting that a company holds once every financial year, at which the board presents the audited financial statements to shareholders and the shareholders formally approve the recurring items that keep the company's governance current: adopting the accounts, declaring any dividend, confirming the auditor, and re-electing directors who are due to retire by rotation. Section 96 of the Companies Act, 2013 makes holding one mandatory for every company registered in India except a one person company (OPC).
Which companies must hold an AGM
Section 96(1) applies to every company incorporated under the Act other than an OPC, which covers private limited companies, public limited companies, companies limited by guarantee, and companies with no share capital at all. A private company being closely held, with no public shareholders and no stock exchange listing, does not exempt it from holding an AGM.
The single exception is the one person company, defined under Section 2(62) as a company with only one member. An OPC has no separate shareholder body to report to beyond that single member, so the accountability function an AGM performs for other companies does not apply in the same way. Every other company, regardless of size, turnover, or how many people actually attend, must hold one.
When must a private company hold its AGM
A company's first AGM must be held within nine months from the close of its first financial year. Every AGM after that must be held within six months from the close of the relevant financial year. On top of both deadlines, Section 96(1) sets an independent ceiling: no more than fifteen months can elapse between the date of one AGM and the date of the next, regardless of when either fell relative to its own financial year end.
The Act also spares a newly incorporated company from holding a second, incorporation-year meeting. Section 96(1) confirms that once the first AGM is held within that nine-month window, the company does not need to hold a separate AGM in its year of incorporation.
Can the AGM deadline be extended?
The Registrar of Companies (RoC), the official who administers company filings in each state, can extend the deadline for an AGM by up to three months. Section 96(1) leaves the extension to the Registrar's discretion, granted "for any special reason," a phrase the Act does not define further. That means the Registrar decides case by case whether the company's stated reason is sufficient. The company applies through Form GNL-1, stating the reason and the period of extension sought.
This extension is not available for a company's first AGM. The relevant proviso in Section 96(1) explicitly limits the extension to "any annual general meeting, other than the first annual general meeting." Since the first AGM already carries a longer nine-month window built into the statute, the Act does not offer a further extension on top of it.
Where and when an AGM can be held
Section 96(2) fixes the AGM to business hours, between 9 a.m. and 6 p.m., on any day that is not a National Holiday, a day the Central Government has specifically declared as such. The meeting has to take place at the company's registered office, or somewhere else within the same city, town, or village where the registered office sits. An unlisted company can hold its AGM anywhere in India if every member provides written or electronic consent in advance.
Notice requirements for an AGM
Section 101(1) of Companies Act, 2013 requires a company to give at least 21 clear days' notice of a general meeting, in writing or electronic mode. "Clear days" excludes both the day the notice is sent and the day of the meeting itself, so the practical lead time runs slightly longer than 21 calendar days in most cases.
The notice must specify the place, date, day, and hour of the meeting, and it must contain a statement of the business to be transacted, under Section 101(2). It has to go to every member, the legal representative of any deceased member or the assignee of an insolvent member, the company's auditor or auditors, and every director, under Section 101(3).
A company can call an AGM on shorter notice if members holding not less than 95 percent of the voting rights entitled to vote at that meeting give their consent in writing or electronic mode. An accidental omission to send the notice to someone entitled to it, or that person's non-receipt of it, does not by itself invalidate the meeting, under Section 101(4).
Quorum for a private company's AGM
Quorum is the minimum number of members who have to be personally present before a meeting can validly transact business. Under Section 103(1)(b), the quorum for a private company's meeting is two members personally present. That figure is a default, not a fixed floor: Section 103(1) opens with "unless the articles of the company provide for a larger number". A private company's articles of association can set a higher quorum than two, and where they do, the higher number governs.
By contrast, a public company's quorum scales with its membership: five members if it has up to 1,000 members, fifteen if it has more than 1,000 but up to 5,000, and thirty if it has more than 5,000, again subject to a larger number in the articles.
If quorum is not present within half an hour of the time fixed for the meeting, Section 103(2) provides that the meeting stands adjourned to the same day the following week, at the same time and place, or to whatever other date, time, or place the board decides.
Can a shareholder send a proxy to an AGM
A proxy is a person a shareholder appoints to attend and vote at a meeting on their behalf, when they cannot attend in person. Under Section 105(1), any member entitled to attend and vote at a meeting can appoint a proxy, who does not need to be a member of the company themselves. The instrument appointing the proxy has to be in writing, filed on Form MGT-11, and deposited with the company at least 48 hours before the meeting, under Rule 19 of the Companies (Management and Administration) Rules, 2014.
A proxy cannot speak at the meeting and can vote only on a poll, not on a show of hands. One person can act as proxy for up to 50 members, provided those members together hold no more than 10 percent of the total voting share capital.
What business is transacted at an AGM
Section 102(2)(a) sorts everything that can come up at an AGM into two categories: ordinary business and special business. Only four items count as ordinary business: considering and adopting the financial statements together with the board's and auditors' reports, declaring a dividend, appointing directors in place of those retiring by rotation, and appointing the auditors and fixing their remuneration. Every other item taken up at an AGM, and everything taken up at any other general meeting, counts as special business.
For each item of special business, Section 102(1) requires the company to annex a statement to the notice setting out the material facts, including the nature and extent of any interest that a director, manager, or other key managerial personnel (and their relatives) has in that item.
Anyone who benefits from an item where the required disclosure was not made holds that benefit in trust for the company and has to compensate the company for it. A defaulting promoter, director, manager, or other key managerial personnel also faces a fine of up to ₹50,000, or five times the amount of the benefit received, whichever is higher, under Section 102(4) and (5).
How to conduct an AGM
Conducting an AGM follows a fixed sequence, from board approval of the notice through to recording the minutes.
The board meets first, to fix the date, time, and venue of the AGM, approve the draft notice together with any explanatory statement for special business, and authorise someone, typically the company secretary, to issue the notice and sign the minutes.
The company then dispatches the notice at least 21 clear days before the meeting, to every member, director, and auditor, either in writing or electronically.
On the day, the chairperson confirms quorum before any business is transacted. Once quorum is confirmed, the meeting works through the ordinary business first, followed by any special business, taking a vote (by show of hands, poll, or e-voting, depending on the company) on each resolution.
After the meeting, the minutes have to be prepared, signed by the chairperson, and entered into a minutes book with consecutively numbered pages within thirty days of the meeting's conclusion, under Section 118.
What happens if a company fails to hold its AGM
Two consequences follow a missed AGM, and they operate independently of each other.
First, Section 97 lets any member of the company apply to the National Company Law Tribunal (NCLT) if the company defaults on holding its AGM under Section 96. The Tribunal can call the meeting itself, or direct that it be called, and can give whatever ancillary directions it thinks fit, including a direction that a single member present in person or by proxy is deemed to constitute a valid meeting on that occasion.
Second, and separately, Section 99 makes the default itself an offence. If a company fails to hold its AGM in accordance with Section 96, or fails to comply with a Tribunal direction under Section 97 or 98, the company and every officer of the company who is in default become punishable with a fine of up to ₹1,00,000, plus a further fine of up to ₹5,000 for every day the default continues. "Officer in default" is a defined category under Section 2(60) that typically covers whole-time directors and other key managerial personnel, rather than every director indiscriminately.
Compliance filings that follow an AGM
Form MGT-7, the company's annual return under Section 92, is due within 60 days of the AGM. It records who owns and manages the company, not its financial performance, and it applies to every company except those eligible for the shorter MGT-7A.
Form AOC-4, which files the company's financial statements with the Registrar under Section 137, is due within 30 days of the AGM at which those statements were adopted.
Where the AGM appoints or reappoints an auditor under Section 139(1), the company files Form ADT-1 within 15 days of the meeting. This is a different trigger from the ADT-1 filing for a company's very first auditor, which the board appoints within 30 days of incorporation under Section 139(6), well before any AGM takes place.
Where the AGM passes a special resolution, such as one altering the articles of association, the company files that resolution using Form MGT-14 within 30 days, under Section 117. A special resolution is a distinct concept from special business: special business refers to what can be on the AGM agenda beyond the four routine items, while a special resolution refers to the higher voting threshold, at least three times the votes against, required to pass certain items regardless of which agenda category they fall under.
FAQs on annual general meeting
What is the due date for AGM?
A private company's first AGM is due within nine months of the close of its first financial year. Every AGM after that is due within six months of the financial year's close, and the gap between any two AGMs cannot exceed fifteen months. The Registrar of Companies can extend a non-first AGM's deadline by up to three months for a special reason.
Is AGM compulsory for private companies?
Yes. Section 96 of the Companies Act, 2013 requires every company other than a one person company to hold an AGM each year, and a private company's closely-held status does not create an exemption. The only company type excused from holding an AGM is the one person company.
What's the difference between AGM and EGM?
An AGM is a mandatory, recurring meeting tied to the financial year, at which a fixed set of ordinary business (accounts, dividend, director rotation, auditor appointment) is always transacted alongside any special business. An EGM (Extraordinary General Meeting) is called on demand, whenever business arises that needs shareholder approval before the next AGM, and everything transacted at it counts as special business.